Is Your Community Prepared for Hurricane Season?
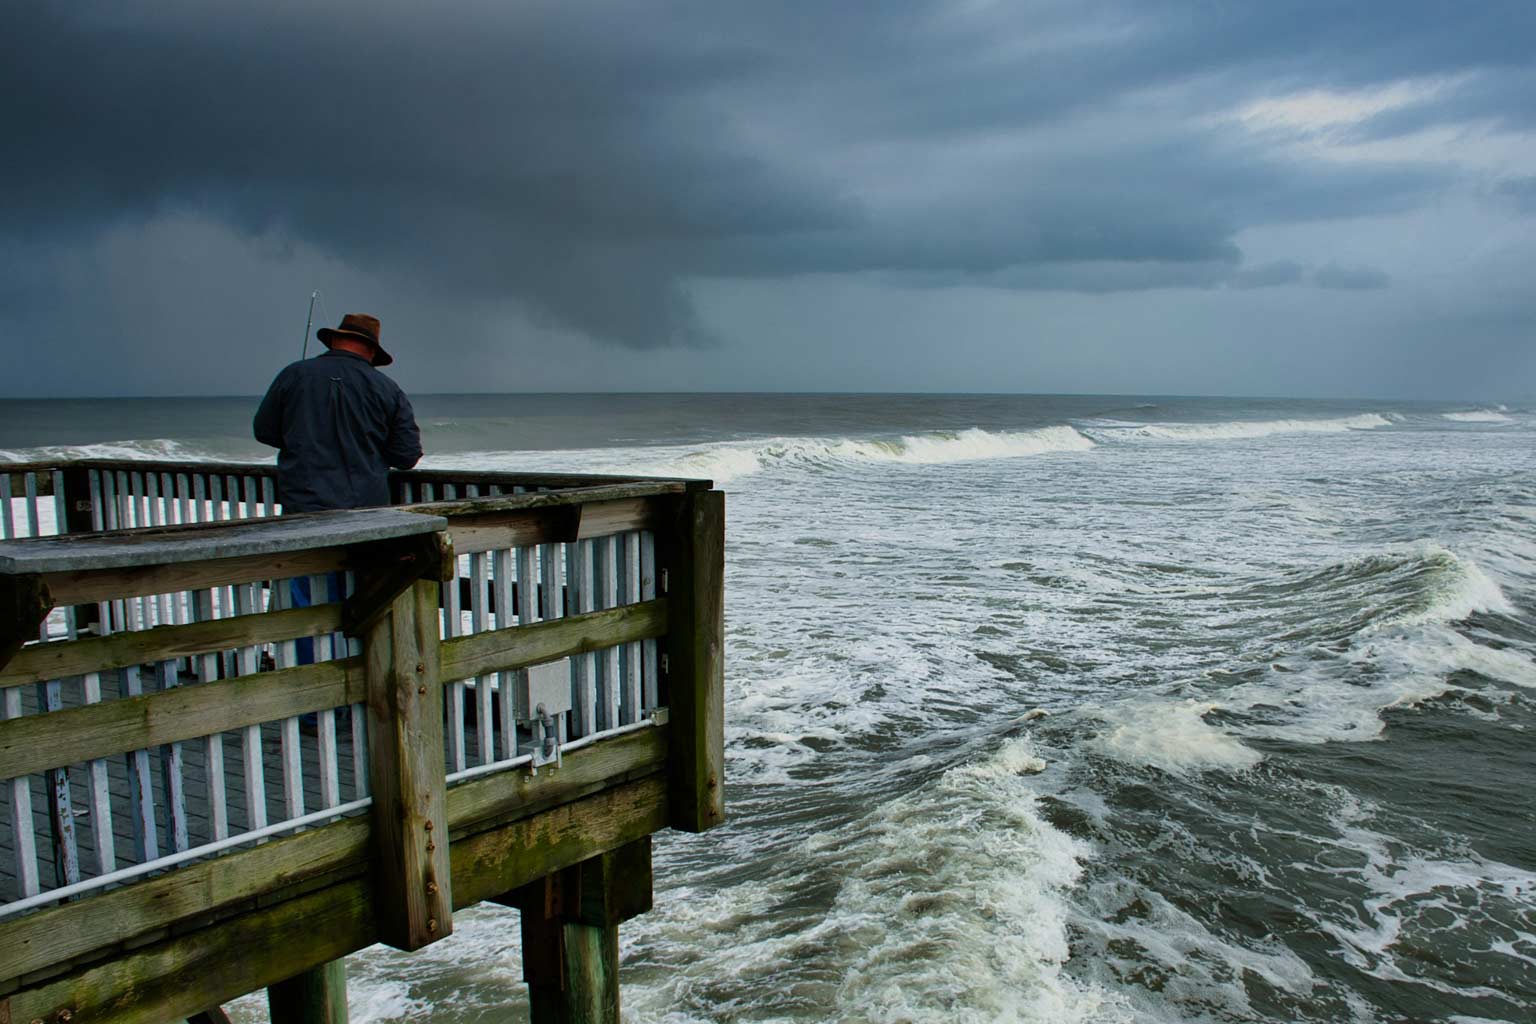
Florida’s hurricane season runs June 1 through November 30, and the associations that come through it with the least damage and disruption are almost always the ones that started preparing months, not days, before a storm formed. Preparation touches more than boarding windows; it spans financial readiness, insurance review, operations, vendor relationships, and the physical property itself. Here’s what a complete plan actually covers. Two terms worth defining first: Emergency board powers: Special authority typically outlined in governing documents or Florida Statutes that lets the board act quickly during a declared emergency (approving emergency repairs, relocating funds) without following the association’s normal notice and voting procedures. Reserve fund: Money set aside for major repairs and replacements, separate from operating funds;, see our related guide on reserve fund health for more. How Should a Board Financially Prepare for Hurricane Season? Cash access matters as much as coverage. Solid HOA hurricane financial
How to Get Through Budget Season Without the Stress
Budget season is stressful for a reason: board members are volunteers juggling day jobs, residents expect answers they don’t always have yet, and the whole process runs on a deadline that doesn’t move. The good news is that most of the stress isn’t really about the numbers – it’s about the process. Fix the process, and the numbers get a lot easier to sit with. A couple of terms worth clarifying first: Budget Season: The period – typically late summer through fall for Florida associations – when boards prepare, review, and adopt the following year’s operating budget, usually finalized at an annual meeting in November or December. Reserve Contribution: The portion of the annual budget set aside for future major repairs, separate from day-to-day operating costs. Why Is Budget Season So Stressful for HOA and Condo Boards? Mostly because it compresses a lot of decisions – some financial, some political
Does Your Community Association Have an Emergency Plan?
Most don’t, and that’s the risk. Government agencies and private businesses maintain formal disaster response plans as a matter of course. Most condo and HOA boards, by contrast, have no documented plan at all until the night a fire breaks out,; a hurricane makes landfall, or a building system fails, and the board is left improvising decisions that affect hundreds of residents in real time. A couple of terms worth defining first: Emergency powers statute: Florida law (F.S. 718.1265 for condominiums, F.S. 720.316 for homeowners’ associations) that grants boards specific authority to act during a declared state of emergency, including access to units, emergency repairs, and certain financial decisions without the usual advance notice requirements. Disaster response plan: A documented, board- adopted plan defining roles, responsibilities, communication methods, and decision-making authority before, during, and after a disaster. Why Does a Community Association Need a Formal Emergency Plan? Because disasters don’t
A Complete Budget Season Planning Guide for Condo and HOA Boards
Florida condominium and homeowners’ associations are legally required to prepare an annual budget – and it’s far more than a formality. Florida’s annual budget requirements sit in statute, and the budget itself becomes the financial plan the entire association year runs on, as well as the benchmark owners use to judge how well the board managed the community’s money. Three terms are worth defining before we walk through the process: Working capital: The association’s operating fund balance – essentially its short-term cash cushion for day-to-day expenses, separate from reserves. Reserve funding: Money set aside in the budget specifically for major future repairs and replacements. Special assessment: A one-time additional charge to owners, typically used when the operating fund or reserves fall short of what’s actually needed. Who Is Responsible for Preparing an HOA or Condo Budget? Who prepares a condo association budget? It starts with the community association manager (CAM),
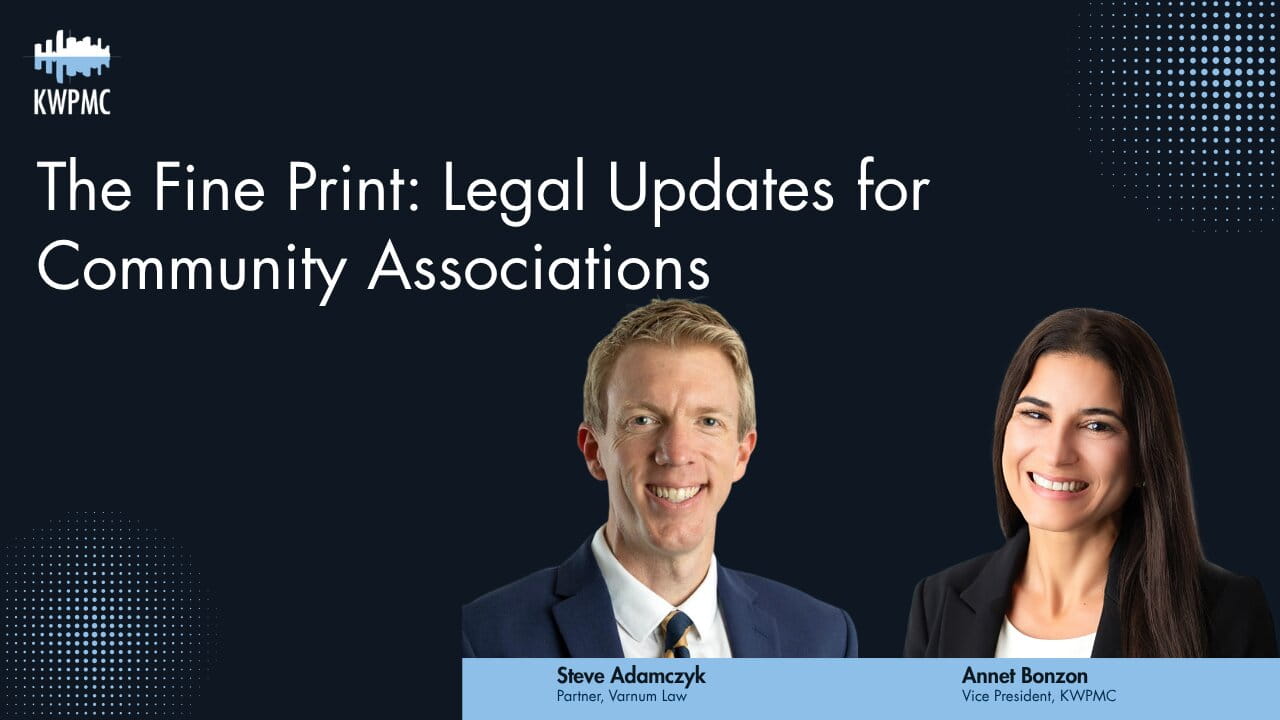
The Fine Print: Legal Updates Every Community Association Should Know
Legal updates can feel overwhelming – but they don’t have to be. That was the framing Alex Martin, Partner at KW Property Management & Consulting (KWPMC), set at the top of KWPMC’s latest legal webinar, The Fine Print: Legal Updates for Community Associations. Joining Martin and KWPMC Executive Vice President Zuly Maribona were Annet Bonzon, KWPMC Vice President and active CAM instructor, and Steven Adamczyk, a Naples-based partner with statewide Florida community association law practice Varnum. The panel covered three developments reshaping condo and HOA governance in 2026: new Fannie Mae reserve requirements, the growing legal risk of AI in board decision-making, and a Florida Supreme Court ruling on firearms in common areas. As always, this recap is for general information only – associations should confirm how these updates apply to them with their own legal counsel. Fannie Mae’s New Reserve Requirements Are Reshaping Condo Financing The most pressing update,